In early 2026, a line of reasoning swept Wall Street with the force of the obvious: if an AI writes software in a few hours, why keep paying Salesforce, SAP or Workday every month? Jefferies gave the thesis a name, SaaSpocalypse, and the market traded it. Oren Greenberg records $285 billion wiped from software stocks in 48 hours; an analysis by Tekkit puts it at more than $1 trillion over twenty-four months; an opinion piece by Jeffrey Sonnenfeld and his co-authors in Fortune says roughly $2 trillion over a year. Three figures, three scopes, three periods: they do not measure the same thing and we are not adding them up. They only give the order of magnitude of the bet.
Six months on, the bet is unwinding. Salesforce reports revenue up 11% to $11.35 billion, and its stock gains 20% in a single session: after fourteen consecutive down sessions, its best rally since 2020. Its churn, per the same analysis, is near historic lows.
What interests us is not the share price. It is that the market has just made, at scale and with real money, the reasoning error that every team makes when it decides to rebuild a tool in-house. It is worth looking at closely, because it cuts both ways.
"It's exhilarating. For about three weeks."
Carlos Diaz tells it best in Silicon Carne, and the scene is recognisable: you open Cursor or Claude Code on a Saturday morning, decide to rebuild your CRM, and a few hours later you have an interface, a customer database, some automations and a nice dashboard. Then you look at your Salesforce invoice and wonder why you pay several thousand dollars a year.
It's exhilarating, and above all very convincing… for about three weeks. Then real life begins.
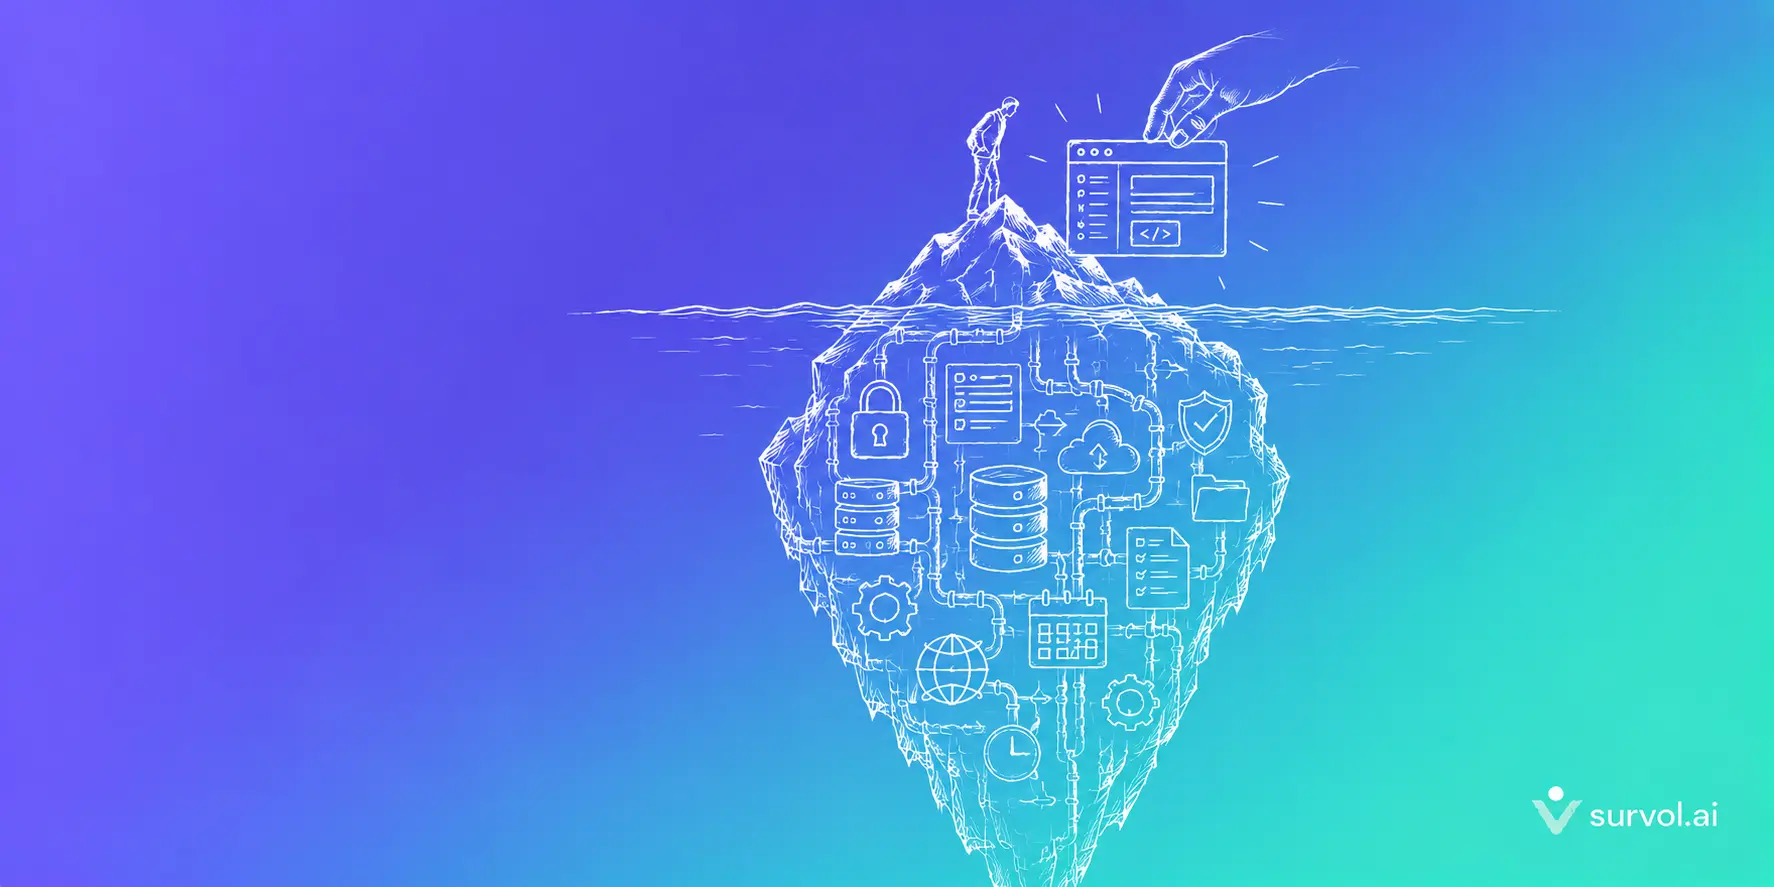
What follows is a list nobody puts in the initial estimate: access rights, authentication, backups, migrations, integrations, business exceptions, compliance rules, service availability, and working out how someone in accounting broke something no engineer had imagined. His conclusion is the single most useful sentence in the whole file: you have not rebuilt an application, you have just committed to maintaining your own enterprise software for the next ten years.
That is exactly the point we made on 15 September about the third of companies walking away from a software purchase: a subscription contains four things that never appear on the invoice (a roadmap, maintenance, compliance carried by a third party, and someone to call). The difference this time is that we have the invoice for the mistake at market scale.
The number everyone quotes, and what it actually measures
The figure circulating in support of the thesis comes from Retool: 35% of enterprises have already replaced at least one SaaS tool with a custom build, and 78% plan to build more this year. Greenberg calls it "technically true but deeply misleading", and his objection is precise: look at which tools are being replaced and you find Zapier-type things, simple integration and automation layers. Not CRM platforms. Not analytics infrastructure.
These aren't SaaS replacements. They're filling the gaps between SaaS tools.
That correction applies to us too. McKinsey measured in August that 32% of organisations had decided against a software purchase; Retool measures that 35% have replaced one. Both figures are true, and neither says what people make them say, because neither says which software. An internal dashboard no vendor was ever going to build for your cross-functional process, and a payroll suite, do not weigh the same inside the same statistic.
Three buckets, and the test that sorts them
The most useful contribution in Greenberg's analysis is to refuse the question "is SaaS dead?" in favour of the only one you can actually decide: which bucket does this particular tool fall into?
- Already gone. Basic content creation, translation, desk research. Tools that were only a UI layer over a foundation model are hit first: Jasper at $49 a month when Claude does the same at $20. Same for simple task-management tools: CNBC reporters built a working Monday.com clone in under an hour for less than $15.
- Announced, not arrived. Complex agentic workflows. Greenberg sees a double gate nobody is pricing in: organisational readiness first (few teams can actually put this into production), reliability second: a model is probabilistic, not deterministic, so you need a QA layer, then a QA layer for the QA layer, then a human to sanity check it. That cost is never in the narrative.
- Moated, and adapting. Data-rich platforms. You do not rebuild a web crawl index on a Saturday morning; nor do you rebuild email deliverability, ISP relationships and DKIM compliance. You can code a form that sends a message; you cannot code the infrastructure that makes it land.
The test that sorts a tool into one bucket rather than another fits on one line: if the tool's value is a UI layer sitting on top of something AI now does natively, it is exposed. Greenberg puts it bluntly (the wrapper is the vulnerability) and adds a figure that says why the barrier is gone: 63% of people doing vibe coding are not developers.
The moat analysts never mention
There is a class of obstacle that appears in no financial model and that every security officer will recognise: SOC 2, granular access controls, audit trails. Someone replaces Loom with a tool hacked together over a weekend; it works fine, until the first certification requirement.
Your CISO isn't signing off on a weekend vibe-coding project handling customer data.
Hence the diagnosis: the market priced replacement risk across the entire customer base when it only sits at the bottom of it: small businesses, perhaps the lower mid-market. A large account's procurement requirements don't look at the demo; they look at the box that has to be ticked. It is the same subject as our 9 October piece on business teams writing code: what decides is not the tool, it is who approves and against which written criteria.
The test that separates narrative from fact: headcount
The most convincing check in the whole file costs nothing and deserves to be copied everywhere: Greenberg compared the share prices of the announced victims with their headcount growth.
Duolingo +76% in two years. Datadog +63%. Figma +55%. Atlassian +52%. HubSpot +40%, while its stock lost roughly half its value over a year. The only real declines: Chegg (−26%) and LegalZoom (−8%), with Adobe flat at zero, which for a company that size is already notable stagnation. The principle travels well beyond the subject:
Stocks can be driven by narrative. Headcount can't.
Chegg is the honest counter-example: homework help was always going to be swept away. The file does not claim nothing dies; it claims the market treated a very heterogeneous list as one block.
What the winners understood before the analysts
Two facts are worth setting side by side. The first comes from the Fortune piece: the Wells Fargo line it quotes, "lower cost of intelligence increases value of incumbent data", turns the thesis inside out. If the agent is cheap, what becomes scarce is not the reasoning, it is the material it reasons over. The same authors report that Agentforce went from $100 million to $1.5 billion in annual recurring revenue in eighteen months, and that Salesforce ingested 104 trillion records last quarter, double the one before. Take it for what it is: an opinion piece, arguing a case.
The second comes from Anthony Bourbon, who notes that SAP took a stake in n8n: about €60 million for just under 1.3% of the capital. His reading of the deal is the right one: what SAP buys is not the code, which it could rewrite, but a developer community and thousands of integrations already in production. His line sums up the whole file: a software vendor's job isn't coding for thirty years, it's winning customers and keeping them. He too has a stake in the story: he is an investor, looking at assets.
He does add the caveat that stops you concluding too fast, and it is to his credit: the position protects, it does not immunise. Siebel ruled customer relationships before Salesforce, Lotus Notes ruled messaging before Outlook. They were unseated in the end, over years, not months.
"They're right. They're just years early."
That is the line the file should close on, and it is Greenberg's. The direction Wall Street anticipated is the right one: capability is advancing, fast. What the market misjudged is the timing, and confusing direction with calendar is an expensive mistake in both directions. Betting that nothing will change is as wrong as betting that everything changes this quarter.
Two caveats before closing. First, the sources in this file are not neutral, and none of them really hides it: Manhattan Associates, which published "the SaaSpocalypse myth", is an enterprise software vendor; Anthony Bourbon is an investor; the Fortune piece defends three named companies; Oren Greenberg advises B2B companies on go-to-market. A market convincing itself it will not die produces a great deal of writing saying it will not die. Second, what holds in their arguments holds because it is checkable (headcount growth, the detail of which tools were actually replaced, certification requirements), not because the authors are persuasive.
What it changes for whoever decides
The build-or-buy question does not arise globally, and that is the practical lesson. It arises tool by tool, with three tests this file hands over for free:
- Is this tool's value an interface, or a material? A wrapper can be rebuilt. Ten years of contact data, a crawl index or a sender reputation cannot.
- Who carries compliance? If the answer changes sides when you build, the cost of building is not the cost of the project.
- What happens at three in the morning? Bourbon's question is the simplest and the most discriminating: when the monthly close goes wrong, who picks up?
And for what you decide to build anyway (which will happen more and more, that is the direction of travel), there remains the part this file describes without naming: the ten-year commitment. A version that carries its origin, a specification that outlives the session that produced it, a promotion that goes through declared checks: that is not comfort, it is what turns an exhilarating Saturday morning into software you can still evolve in 2036. That is Survol's work, and I say it plainly rather than leave it to be guessed, but the rule holds with or without us.
Sources
- Oren Greenberg, "The SaaSpocalypse Is Real. It's Also Mostly Wrong.", 20 February 2026, updated 6 April 2026. The $285 billion in 48 hours, the name coined by Jefferies, the Retool figures (35% / 78%), the three buckets, the double gate, the compliance moat and the headcount growth all come from it.
- Carlos Diaz, Silicon Carne, "Le SaaS Apocalypse n'aura pas lieu !", 7 September 2026. The Saturday morning scene, the three weeks and the ten-year commitment come from it. The copy we have carries no URL, so it is not linked here.
- Tekkit, "La 'SaaSpocalypse' n'aura pas lieu", 31 August 2026. Salesforce's results (+11%, $11.35 billion, +20% in one session), the churn level and MCP adoption come from it.
- Anthony Bourbon (Blast.Club), "La SaaSpocalypse n'aura pas lieu", LinkedIn, 15 June 2026. SAP's stake in n8n, the Siebel / Lotus Notes comparison and the three-in-the-morning question come from it. The author is an investor.
- Jeffrey Sonnenfeld, Steven Tian and Stephen Henriques, "The SaaSpocalypse that wasn't", Fortune, 26 August 2026. The ~$2 trillion, the Wells Fargo quote and the Agentforce and Slack figures come from it. An opinion piece.
- Manhattan Associates, "The SaaSpocalypse Myth and the Rise of Native, Built-In AI", 17 June 2026. The "deterministic spine" idea and the shift from prompt engineering to context engineering come from it. Published by an enterprise software vendor.